

Wash Sale Rule
The wash sale rule is an IRS regulation designed to prevent invedstors from claiming artificial tax losses. It applies when you sell a stock or security at a loss and purchase the same or a sub stantially idential asset within a specific 61-day window. While tax - loss harvesting is a smart strategy to lower your tax bill, triggering a wash sale will delay your tax break. Understanding the rule is vital for anyone looking to optimize their investment portfolio without running afoul of tax laws.
How to time a Tax-Loss Sale Safely:
Case 1:
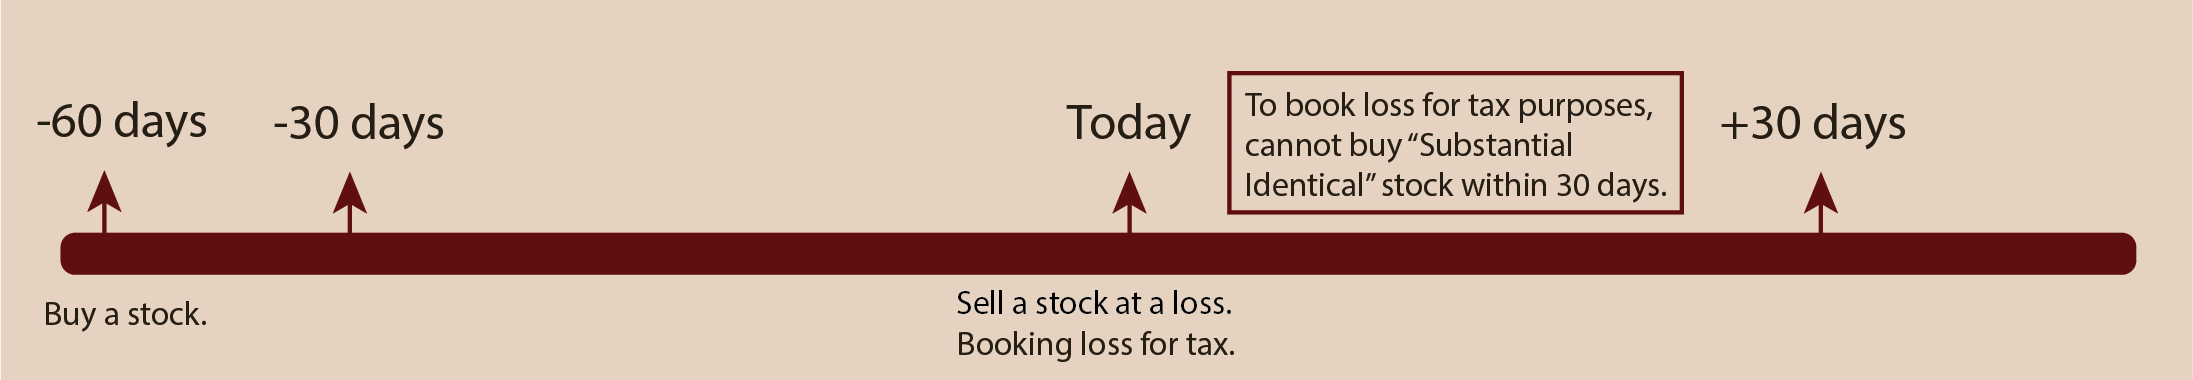
Hypothetical Example:
An investor holds shares of a Vanguard S&P 500 ETF (Ticker: VOO) in a taxable brokerage account. Due to market fluctuations, the current market value of the position falls below the original purchase price. The investor decides to sell the VOO shares to realize a capital loss, intending to use that loss to offset other taxable capital gains.
If you sell an S&P 500 ETF (like VOO) at a loss and immediately buy another (like SPY), the IRS may view them as "substantially identical" because they track the same index, triggering a wash sale that disallows your tax loss. To mitigate this regulatory risk while maintaining market exposure, you can invest the proceeds into a Total Stock Market ETF, which tracks a fundamentally different benchmark. After the restricted 30-day window closes, you retain the flexibility to reallocate back into your preferred S&P 500 fund.
Trying to manage a sudden windfall?
Case 2:
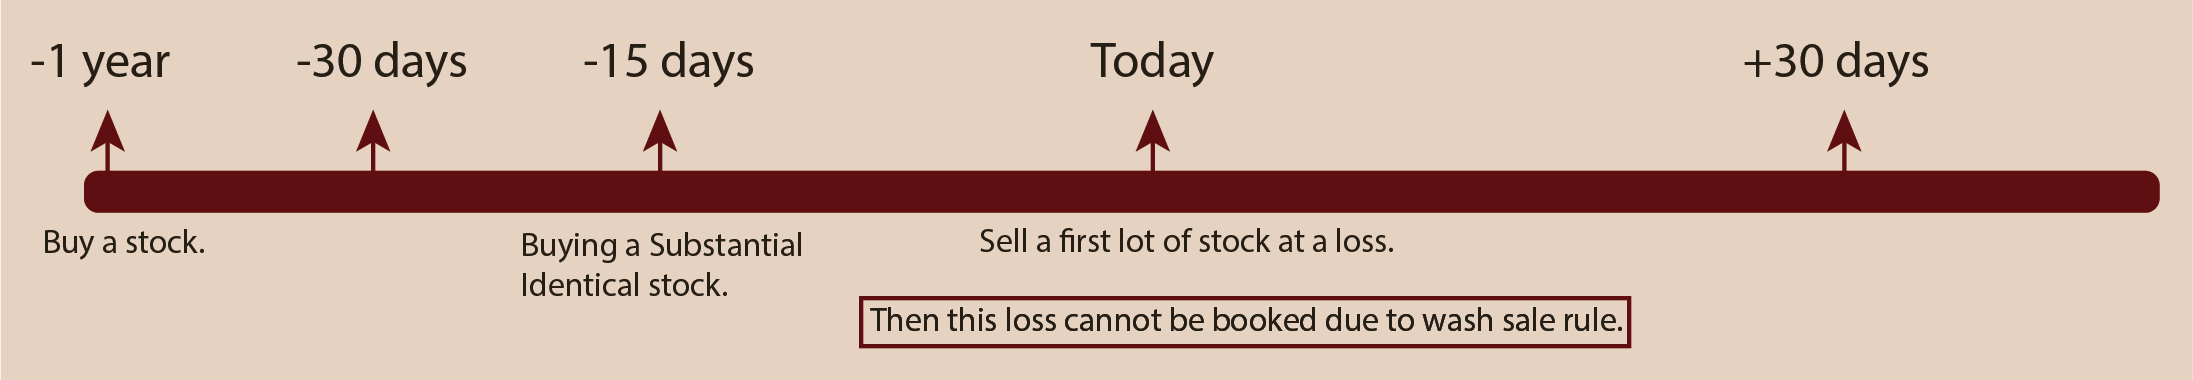
Hypothetical Example:
An investor maintains a position in a Vanguard S&P 500 ETF (Ticker: VOO) within a taxable brokerage account and utilizes an automated investment plan to purchase additional shares every 30 days. Following a market correction, the value of the original shares falls below their initial purchase price. The investor decides to sell those specific shares to realize a capital loss for tax-loss harvesting purposes.
Because the automated recurring purchase acquired identical shares of VOO 30 days prior to the liquidation of the original position, the transaction enters the 61-day wash sale window. Under IRS guidelines, a buy execution occurring within the 30-day period preceding a loss sale is viewed as a replacement of the asset.
This unintended overlap triggers the wash sale rule, meaning the capital loss cannot be used to offset other taxable gains on the current year's return. To mitigate this risk, investors must coordinate any manual sales around the 61-day window, or temporarily pause automatic investment plans on identical or substantially identical assets.
Other Common Wash Sale Mistakes
Cross-Brokerage Trading: Executing a loss sale of a security at one financial institution and purchasing a substantially identical asset through a different broker within the 61-day window still triggers the rule. Automated tracking systems at individual brokerages may not catch this, leaving the compliance burden entirely on the taxpayer during tax preparation.
Spousal Account Traps: The IRS treats married couples as a single economic unit for wash sale purposes. Selling an asset at a loss in your personal portfolio while your spouse simultaneously buys a substantially identical security in their separate account disallows the loss.
Taxable to Tax-Advantaged Transfers: Selling a security at a loss in a standard taxable brokerage account and buying a substantially identical asset inside a tax-advantaged account—such as a Traditional IRA, Roth IRA, or 401(k)—violates IRS Revenue Ruling 2008-5. This specific trigger permanently denies the loss deduction, as you cannot add the disallowed loss to an IRA's cost basis.
Derivative and Option Overlaps: The wash sale rule explicitly includes contracts to acquire substantially identical property. Selling a stock at a loss and immediately buying a call option on that exact same underlying stock will trigger a wash sale.
Simultaneous Long and Short Positions: Selling an S&P 500 ETF to harvest a loss while simultaneously taking a short position in an identical or highly correlated S&P 500 fund to hedge risk creates substantial audit exposure. While explicit IRS guidance on specific cross-fund shorting is nuanced, tax authorities closely scrutinize transactions that lack genuine economic substance or risk change.
Turning Market Dips into Savings
When the stock market experiences a downturn, most investors see it purely as a temporary loss. Strategic investors, however, see an exclusive window of opportunity. Through professional Tax-Loss Harvesting, we turn market volatility into immediate tax credits that can significantly lower your annual tax bill.
Think of it as finding money hidden inside your portfolio. By systematically selling underperforming assets to capture capital losses, we can use those losses to directly offset your capital gains from other investments, real estate sales, or business income. If your losses exceed your gains, you can even use them to offset up to $3,000 of your ordinary income each year, rolling any remaining balance forward into future tax seasons.
Why Partner With a Professional?
While the concept sounds simple, navigating the rigid logistics of the IRS 61-day wash sale window requires absolute precision. A single mistimed trade across your personal accounts, your spouse’s portfolio, or an automated retirement account can permanently invalidate your tax deduction.
We eliminate the guesswork and human error by deploying institutional wealth technology to manage your portfolio:
Continuous Algorithmic Scanning: We don't wait until December to look for tax savings. Our software monitors your portfolio year-round, capturing sudden market drops the moment they occur.
Seamless Market Exposure: We instantly redeploy your harvested capital into strategic, non-identical replacement assets. Your money stays fully invested in the market, ensuring you never miss a sudden rebound.
Cross-Account Protection: Our systems aggregate your taxable portfolios and retirement accounts under one dashboard, blocking the accidental automated purchases or dividend reinvestments that trigger IRS penalties.
Tax-loss harvesting is one of the few legal ways to boost your portfolio's net, after-tax return without increasing your market risk. Let us handle the complex regulatory tracking so you can keep more of what you earn.
If this strategy interests you, do contact us to evaluate of tax loss harvest for your specific situation
Disclaimer: This information is provided strictly for educational purposes and general financial literacy. Tax laws are complex and automated tools do not guarantee specific tax outcomes or protect against market loss.. The integration of options, short positions, and multi-account trading creates highly complex tax scenarios. This text does not constitute legal, tax, or individualized investment advice. You must consult with a certified public accountant (CPA) or a qualified tax advisory professional to evaluate your specific situation prior to executing these strategies
Trying to manage a sudden windfall?